Posted On: Oct 2, 2026
Author: Jason H.
escrow budgeting first-time-homebuyer
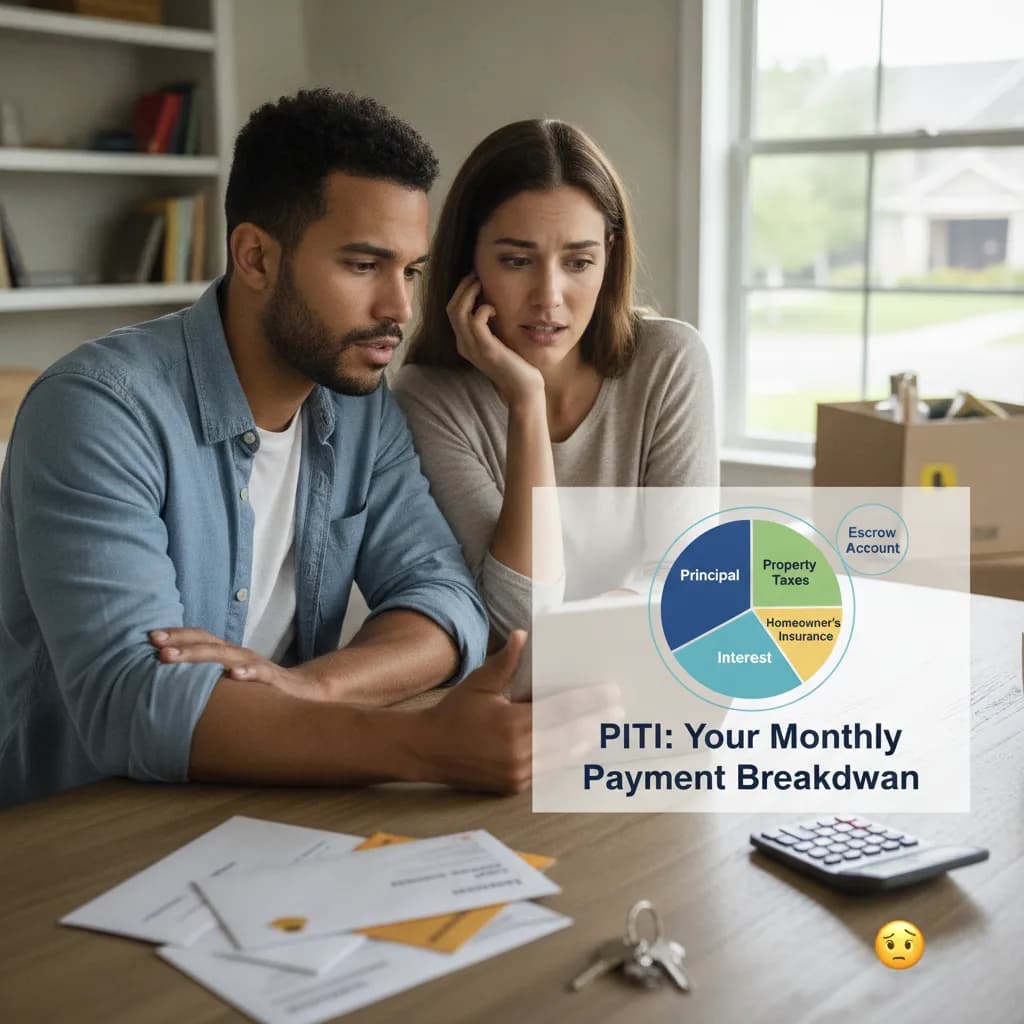
You’ve signed the closing papers, unpacked the last box, and are settling into your new life as a homeowner. Then, the first mortgage statement arrives. You look at the total amount due and your brow furrows. Wait, why is this number higher than I expected?
Welcome to one of the most common points of confusion for first-time homeowners: the escrow account. It's the reason your total monthly payment—often referred to as PITI—is more than just what you’re paying toward your loan balance. But fear not. Once you understand it, your escrow account is less of a mystery and more of a helpful budgeting tool.
Let’s break it down.
Think of an escrow account as a managed savings account that your mortgage lender holds on your behalf. Every month, a portion of your total house payment is diverted into this account. The lender then uses the money in this account to pay for two of your biggest home-related expenses: your property taxes and your homeowner’s insurance premiums.
Your total monthly payment is often abbreviated as PITI:
Essentially, you’re paying your annual tax and insurance bills in small, manageable monthly installments instead of getting hit with two massive bills once or twice a year.
From the lender's perspective, an escrow account is all about risk management. Your home is the collateral for their loan. They need to protect that investment.
While it protects the lender, it also benefits you by smoothing out your annual budget and making sure these critical bills are never missed.
This is the part that catches most homeowners by surprise. Once a year, your lender will conduct an escrow analysis. They review your account to make sure they're collecting the right amount of money.
They compare two things:
Based on this analysis, your monthly payment can go up or down. Here are the two most common outcomes:
1. Escrow Shortage
This happens when your property taxes or homeowner's insurance premiums increased during the year. The lender still paid the bills for you, but the money in your escrow account wasn't enough to cover the full amount. Now, you have a shortage.
Your lender will typically give you two options:
2. Escrow Surplus
This is the happier scenario. It happens if your taxes or insurance premiums went down, and you ended up overpaying into your account. By law, if the surplus is over a certain amount (usually $50), the lender must mail you a check for the difference.
For some homeowners, yes. Once you’ve built up enough equity in your home—typically 20%—you can ask your lender to waive escrow.
For most new homeowners, letting the lender manage escrow is the simplest and safest path, at least for the first few years.
Understanding your escrow account is a huge step in mastering your home's finances. It transforms your house payment from a single, mysterious number into a predictable plan for covering your home's core obligations.
But what about the costs that aren't predictable? Escrow handles taxes and insurance, but it can't help you when the furnace dies in January or the roof starts leaking after a storm. That’s where a different kind of planning is required.
This is exactly why Properteer was created. Properteer takes the guesswork out of homeownership by creating a personalized financial forecast for your specific property. Our AI-powered platform tracks the age of your home's core systems, predicts when they’ll need replacement, and helps you build a realistic budget for both routine maintenance and those big-ticket items. Stop reacting to financial surprises and start planning with confidence. Visit Properteer.ai to build your home's financial fortress and truly understand the full cost of ownership.
Q: What is an escrow account?
A: It's a special savings account managed by your mortgage lender to pay your estimated property taxes and homeowner's insurance premiums on your behalf. A portion of your monthly mortgage payment funds this account.
Q: Why did my monthly mortgage payment suddenly go up?
A: Your payment likely increased because your property taxes or homeowner's insurance premium went up. Your lender performed an annual escrow analysis and adjusted your payment to cover the new, higher costs and any shortage from the previous year.
Q: What is an escrow shortage?
A: A shortage occurs when the actual cost of your taxes and insurance was higher than the amount your lender collected from you in your monthly payments. You'll need to make up this difference, either in a lump sum or through higher mortgage payments for the next year.
Q: Can I pay my own property taxes and insurance instead of using escrow?
A: Sometimes. If you have enough equity in your home (typically 20% or more), you can request that your lender waive the escrow requirement. This means you become responsible for saving for and paying these large bills directly when they are due.